Key Points
- Vaping Products Duty takes effect on 1 October 2026, the first time e-liquids have carried excise duty in the UK.
- The rate is a flat £2.20 per 10ml of vaping liquid, charged on volume regardless of nicotine strength, nicotine-free products included.
- A Vaping Duty Stamps scheme launches alongside the duty. Every product made or imported from 1 October must carry a stamp on its retail packaging, and from 1 January 2027 only stamps with a digital tracking feature can be used.
- Civil penalties for dealing in unstamped product apply from 1 October 2026. Criminal offences for possessing, selling or displaying unstamped product, with unlimited fines and possible custodial sentences, apply from 1 April 2027.
- HMRC registration for manufacturers, importers and warehousekeepers opened on 1 April 2026, with 45 working days recommended for approval.
- Tobacco duty rises by a commensurate amount on the same day, £2.20 per 100 cigarettes, to keep the price incentive for smokers to switch to vaping.
- HMRC estimates the duty will affect 5.1 million people who vape in the UK, with revenue certified by the OBR at £565 million a year by 2030-31.
From Wednesday 1 October 2026 every millilitre of vaping liquid sold in the UK carries excise duty for the first time, at £2.20 per 10ml, and every bottle or pod that is made or imported from that day has to carry a duty stamp on its packaging before it can be sold. The rate was set in the Autumn Budget of October 2024 and the law is Part 4 of the Finance Act 2026. HMRC put out its one month warning on 1 September and has said plainly that a manufacturer or importer without approval by Wednesday cannot produce in the UK and may not be able to trade.
So what does it mean for the person buying a 10ml bottle, the shop selling it, and the importer bringing it in? Three different things, on three different dates, and the article goes through them in that order.
What The £2.20 Adds At The Till
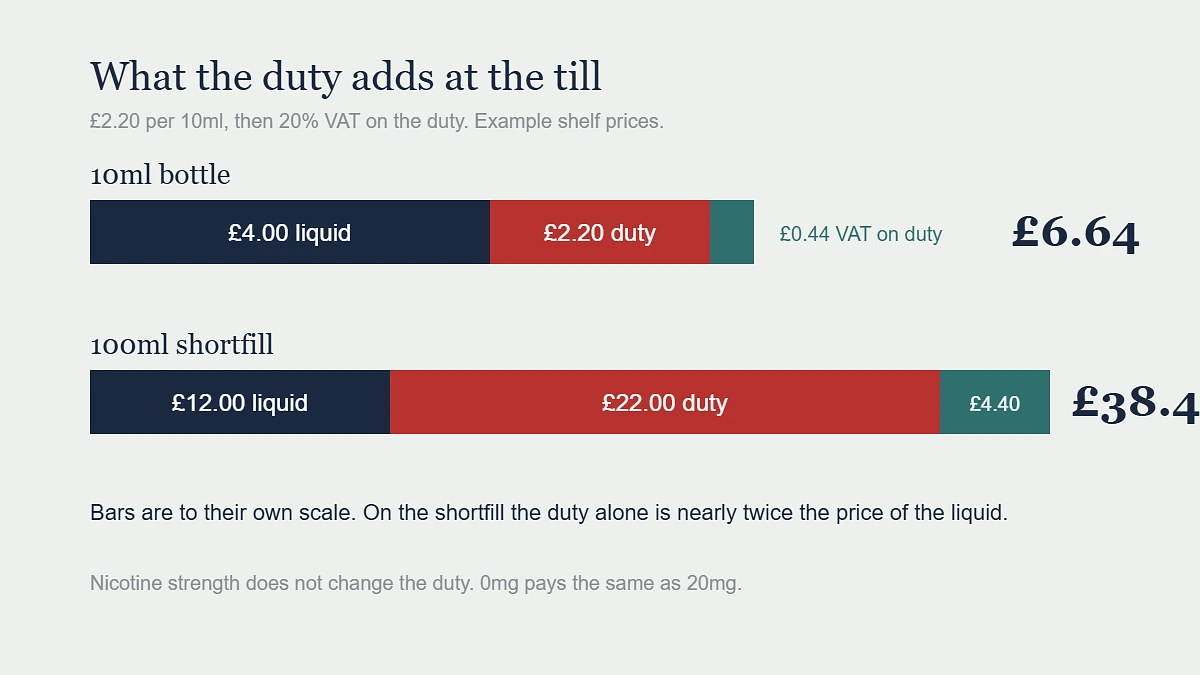
The duty gets charged on volume and nothing else. Nicotine strength does not come into it, and a nicotine-free liquid will pay exactly what a 20mg liquid pays. VAT at 20% then goes on top of the duty-inclusive price, so a 10ml bottle will carry £2.64 more, not £2.20.
| Product | Duty | Duty plus VAT | What that does to a typical price |
|---|---|---|---|
| 10ml bottle, any strength | £2.20 | £2.64 | about £4 becomes about £6.64 |
| 2ml prefilled pod | £0.44 | £0.53 | a £2.50 pod becomes about £3.03 |
| 100ml shortfill | £22.00 | £26.40 | a £12 bottle becomes about £38 |
Whether the whole £2.64 reaches the shelf remains, in HMRC’s words, a commercial decision, so some brands will absorb a little of it for a while. The shortfill line deserves a second look. A 100ml bottle that sold for £12 was the cheap way to vape, and after Wednesday the duty on it alone is nearly twice what the liquid cost. I think the shortfill market as it has existed in the UK is over by Christmas, and the 10ml bottle will come back as the standard unit, which is what a flat rate rather than a tiered one does in practice.
Why Zero Nicotine Pays The Same As 20mg
The government had proposed 3 rates in the Spring Budget 2024 consultation: £1 per 10ml for nicotine-free liquid, £2 for up to 10.9mg per ml, and £3 for 11mg and above. The Treasury dropped it for a single flat rate in the October 2024 Budget.
The reasons it gave were practical rather than principled. A tiered rate would have needed nicotine testing at points along the supply chain, and the consultation responses said that was a cost and a delay the trade could not carry. A flat rate can be checked with a measuring jug.
The consequence, and this has not had much attention, is that the duty gives no reward for stepping down in strength. Someone moving from 20mg to 10mg to 3mg over a year, which is the route the NHS quit services describe, pays the same duty at every step. That was a design choice, and I would have argued with it, because it taxes the exit from nicotine at the same rate as the entry.
The Stamp On The Pack, And The Date HMRC Moved
Alongside the duty comes the Vaping Duty Stamps Scheme, modelled on the stamps that have sat on cigarette packs for years. From Wednesday every vaping product released for sale in the UK must carry a stamp, fixed so that the packaging cannot be opened without breaking either the stamp or the pack.
There are 2 kinds of stamp, and the dates on them changed over the summer:
- Transitional stamps carry physical security features only. HMRC’s original plan had them on sale until 31 August and banned from packs after 30 September. After industry feedback that was pushed back, and they can now be bought until 30 November 2026 and affixed until 31 December 2026.
- Digital stamps carry a scannable feature and have been on sale since 1 September 2026. From 1 January 2027 no other stamp can be put on a product.
- Nothing stamped, transitional or digital, could be released for sale before 1 October.
- Overseas manufacturers cannot buy stamps themselves. They need an HMRC-approved UK representative to hold the approval and order the stamps.
The digital stamp changes enforcement more than the duty does. Each one is scanned as the product moves, so HMRC can see where a bottle was stamped, by whom, and when it left duty suspension, through an app from the stamp supplier. Stamps that are not activated within 12 months of issue attract a penalty on their own.
What A Shop Can Still Sell Until 31 March 2027
A retailer or wholesaler that only sells duty-paid product does not need HMRC approval at all, though they do need to know which stock came in when.
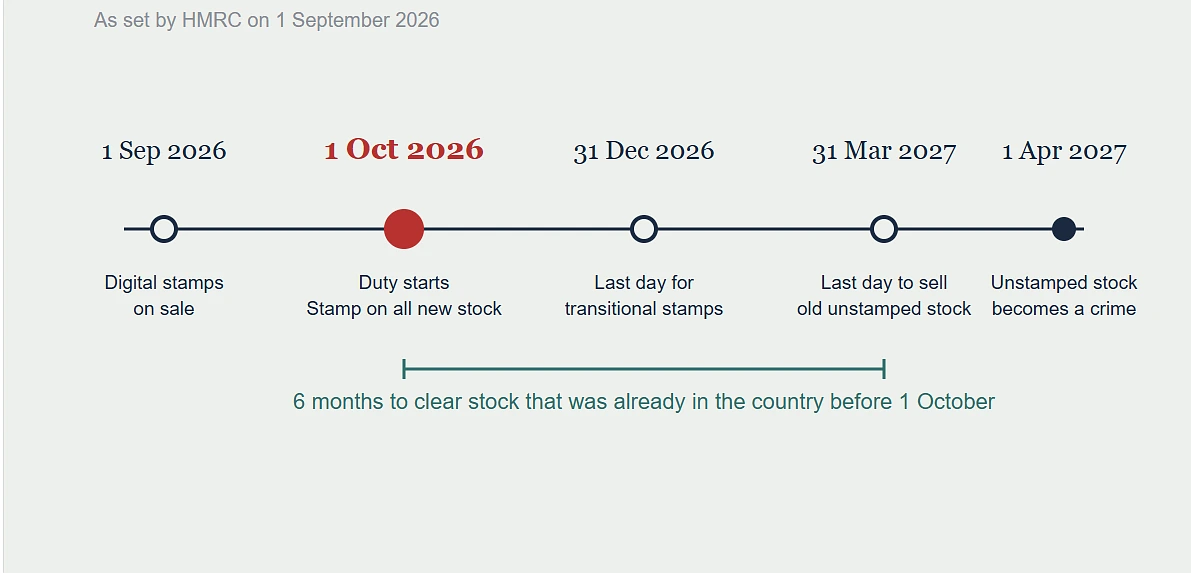
- Stock produced or imported before 1 October 2026 can be sold unstamped until 31 March 2027. That is the 6 month grace period.
- Anything made or imported on or after 1 October must be stamped, whoever is selling it.
- HMRC’s guidance tells a shop offered unstamped product after Wednesday to keep evidence of why it is unstamped, meaning proof it was in the country before 1 October, and not to buy it if that evidence is not there.
- From 1 April 2027 no unstamped product can be held, displayed or sold, whenever it was made. Unsold old stock has to be gone, returned or destroyed by 31 March.
The 6 months belongs to the stock, not to the shop. A shop that buys unstamped liquid in December because it is cheap has bought something it cannot lawfully sell after March, and HMRC has already said there is no compensation for stock that becomes unsellable.
What Happens To A Business That Did Not Apply
Applications for approval opened on 1 April 2026 and HMRC said the process could take 45 working days, which put the sensible application date around 20 July. Rachel Nixon, HMRC’s Director of Indirect Tax, said on 1 September that businesses without approval by 1 October “cannot produce vaping products in the UK and may be unable to trade”. I read that as HMRC telling the last of the importers that the door has closed rather than warning them it is closing.
The Finance Act 2026 has the sanctions arriving in 2 stages:
- From 1 October 2026, section 125: a civil penalty for selling, offering or dealing in unstamped product packaged for retail sale, worked out per retail unit and increasing with repeat failures over a 24 month period. Seizure of the goods sits alongside it.
- From 1 April 2027, sections 130 and 131: criminal offences for possessing, transporting, displaying or dealing in unstamped product, and a separate offence for the manager of premises who permits it. Conviction carries an unlimited fine, imprisonment, or both.
- Courts can also ban premises from operating as a vape shop where criminal dealing in stamps is proved, which is aimed at the pattern of the same shop reopening under a new name and a new director.
- Both criminal sections carry the same defence, proving you did not know, suspect or have reason to suspect the product was unstamped. That defence gets made out of supplier paperwork, so the invoices and delivery notes from before 1 October will matter for a long time after it.
The £2.20 Goes On Cigarettes Too
The vaping duty arrives with a one-off tobacco duty increase of £2.20 per 100 cigarettes, or per 50g of hand rolling tobacco, on the same day. The pairing exists to keep the price gap between smoking and vaping where it was, because the Treasury’s own impact work named the risk the other way round: tax vaping alone and some heavy vapers go back to cigarettes.
The money side has grown since the first estimates. The Treasury expects the duty to raise more than £550 million a year by 2030-31. Tobacco duty already brings in around £8 billion a year, so vaping has been fitted into the same frame, a smaller pipe running into the same tank.
The Disposables Ban 16 Months Ago
Single-use disposable vapes have been illegal to sell in the UK since 1 June 2025, nicotine-free ones included. They had been the cheap way in, at £4 to £6 a device, and the ban moved a large part of the market onto prefilled pods and refillable kits with 10ml bottles. I see the logic of the sequence, ban the format first and tax the liquid second, and I also see who it lands on twice: the person who did what they were told last summer and moved to a refillable, and now pays again on the bottle.
For them the arithmetic still favours the refillable, whatever the duty does to it. A 10ml bottle at £6.64 is far cheaper per millilitre than pods, even after duty, and a shortfill is no longer cheaper than either.
What Is Fixed And What Is Still Moving
The rate stays at £2.20 and the start date stays at Wednesday, neither having moved since October 2024. What has moved is the stamp timetable, twice, and HMRC has said it will raise awareness with the retail sector “later in 2026”, which, for a scheme that starts in 6 days, reads oddly. The first monthly duty returns from approved businesses fall due after the October period closes. After 31 March 2027 an unstamped bottle on any shelf in the country will be an offence rather than old stock.
References
- One month until Vaping Products Duty and the Vaping Duty Stamps Scheme start, HMRC, 1 September 2026.
- HMRC says UK businesses should apply now for Vaping Products Duty, HMRC, 1 April 2026.
- Handling wholesale or retail vaping products in the UK, GOV.UK guidance.
- Vaping duty stamps, penalties and sanctions, CC/FS87, HMRC.
- Finance Act 2026, Part 4, Vaping products duty.
- Key messages for audience groups, Vaping Products Duty communications resources, GOV.UK, updated 1 September 2026.
- Vaping products duty, Spring Budget 2024 measure, Deloitte.